The Evolution of Digital Assets: From Investment to Everyday Spending
The world of digital assets is undergoing a fascinating transformation. A recent study by PYMNTS Intelligence and Paymentology reveals a significant shift in consumer behavior and expectations. While digital assets have already captured the attention of many, the real challenge lies in making them a seamless part of our daily transactions.
Bridging the Gap Between Ownership and Usage
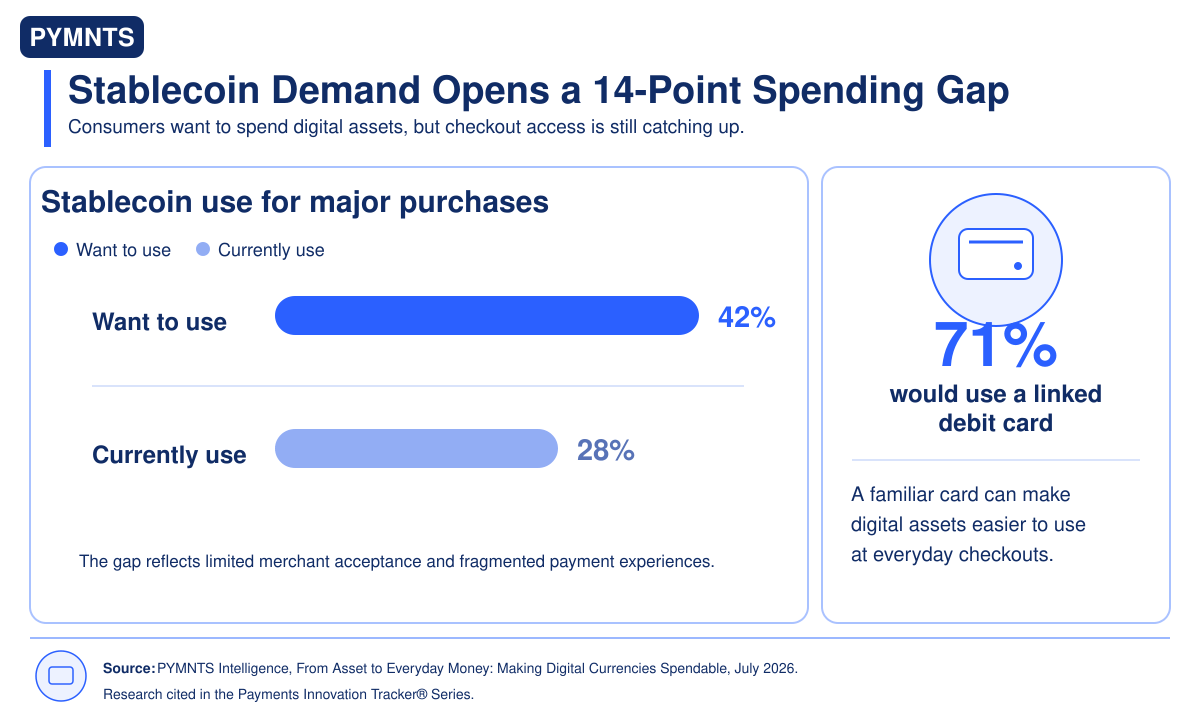
The study highlights a 14-percentage-point gap between consumers who own digital assets and those who use them for everyday purchases. This gap is intriguing because it indicates that the initial excitement of investing in cryptocurrencies and stablecoins is evolving into a desire for practical utility. People are no longer just curious about these assets; they want to spend them like regular money.
What many don't realize is that this shift in mindset is a game-changer. It challenges the traditional boundaries between investment and spending, blurring the lines between the two. In my opinion, this is a natural progression as digital assets mature and find their place in our financial ecosystem.
The Power of Familiarity
One of the most insightful findings is that 71% of stablecoin holders would use a linked debit card to spend their assets. This preference for familiar tools is a testament to human behavior. People are more likely to embrace new technologies when they can integrate them into existing habits. By connecting digital assets to traditional banking apps, cards, and payment networks, we're essentially making the transition less daunting.
Personally, I find this approach brilliant. It's like introducing a new flavor of ice cream to a familiar brand—the essence changes, but the experience remains comfortable. This strategy could be the key to unlocking the full potential of digital assets in the mainstream market.
Trust and Convenience
Trust is a critical factor in the adoption of any new financial system. The study suggests that consumers are more inclined to trust their existing banking or FinTech apps for crypto and stablecoin wallets. This preference for known entities is understandable and could give banks and FinTechs a significant advantage in the digital asset space.
What this really suggests is that the future of digital assets might be closely tied to traditional financial institutions. If banks and FinTechs can provide a seamless, user-friendly experience, they could become the gatekeepers of this new financial frontier. However, they must act swiftly, as the crypto space is known for its rapid innovations.
Beyond Consumer Spending
The potential of digital assets extends far beyond individual consumers. Monthly crypto card spending has skyrocketed, and stablecoins are making their mark in cross-border business payments. The allure of faster settlement, reduced costs, and access to stable value is undeniable for businesses.
In my analysis, this is just the tip of the iceberg. As more businesses recognize the benefits, we could see a significant shift in how international trade is conducted. Digital assets have the potential to revolutionize global commerce, making it more efficient and cost-effective.
Overcoming Barriers
Despite the growing demand, barriers persist. Limited merchant acceptance, transaction costs, volatility, and fraud concerns are significant hurdles. These challenges are not unique to digital assets but are amplified due to their novelty.
Addressing these issues requires a collaborative effort from the entire ecosystem. Merchants, payment processors, and digital asset providers must work together to create a more accessible and secure environment. If we can streamline the user experience and mitigate risks, the sky's the limit for digital asset adoption.
A Measured Yet Optimistic Outlook
The report concludes with a balanced perspective, suggesting that linked cards, real-time conversion, and modern issuer processing can make digital assets more spendable. This approach doesn't require consumers or merchants to start from scratch, which is a huge advantage.
Personally, I think this is a realistic and achievable goal. By leveraging existing infrastructure and adding a layer of innovation, we can make digital assets a viable alternative to traditional currencies. The key is to focus on user experience and build trust, one transaction at a time.
In conclusion, the journey of digital assets from investment vehicles to everyday spending tools is an exciting evolution. It's a testament to human adaptability and our constant search for more efficient ways to manage our finances. As we navigate this transformation, one thing is clear: the future of money is digital, and it's closer than we think.